Growth slows across most regional markets as buyer demand softens nationwide

Regional dwelling values across Australia edged down 0.1% in the three months to July, outperforming a 2.5% decline recorded across the combined capital cities, according to the latest Cotality Regional Market Update.
Of Australia's 50 largest regional Significant Urban Areas (SUAs), 47 recorded slower growth compared with the previous quarter, and 22 posted outright declines in home values.
"Regional markets have consistently outperformed the capital cities since housing conditions began to soften in late 2025, but even the regional markets are now being impacted by the broader market slowdown," said Gerard Burg, head of research at Cotality Australia.
"Relative affordability continues to attract buyers to many regional markets and support internal migration from the capitals. However, softer buyer demand is becoming more evident across the country, with fewer markets recording the strong growth seen earlier this year."
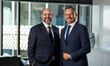
 Burg (pictured right) attributed the broader national downturn to weakness that first emerged in Sydney and Melbourne, driven by high interest rates and affordability pressures, before spreading nationally as consumer confidence fell and investor activity declined.
Western and South Australia lead
Regional areas in Western Australia and South Australia posted the strongest quarterly growth nationally, with dwelling values rising 2.1% in both states. Port Pirie led South Australia with a quarterly gain of 6.7%, while Kalgoorlie-Boulder (6.4%) and Geraldton (3.8%) were the strongest performers in Western Australia.
"Growth across Western Australia remains the strongest in the country as markets with buoyant local economies and relatively affordable housing markets are proving more resilient as buyer demand becomes increasingly selective," Burg said.
"We're no longer seeing growth concentrated in the lifestyle markets that benefited most from spillover demand we saw during the market's prolonged upswing. Instead, buyers are gravitating towards regional centres where their dollar stretches further and local demand is supporting housing values."
Regional Queensland values were flat over the quarter. The Gold Coast, Sunshine Coast, and Cairns each recorded declines of 0.8%, 0.5%, and 0.6% respectively, while Maryborough (2%), Gladstone (1.6%), and Townsville (1.2%) posted gains.
"Queensland has been one of Australia's standout regional performers over the past few years, but we're starting to see a more selective market emerge. As higher-value markets lose momentum and buyers become more cautious, we're seeing demand swing to more relatively affordable regional centres," Burg said. "Higher interest rates have reduced borrowing capacity and buyers are more price sensitive so they're looking for value areas, which has supported demand in regional centres such as Maryborough, Gladstone and Townsville."
Regional New South Wales and Victoria recorded the weakest conditions nationally. In NSW, the steepest declines were in Coffs Harbour (-3.3%), Goulburn (-3.2%), and Nelson Bay (-3%), while Geelong (-1.2%) and Warragul-Drouin (-1.5%) led falls in Victoria. Inland markets including Dubbo (3.9%), Tamworth (2.2%), and Albury-Wodonga (2%) continued to record comparatively solid growth.
Selling conditions soften
Median selling times increased in 44 of the 50 largest regional SUAs during the quarter. Kalgoorlie-Boulder remained the fastest-selling regional market nationally, with a median time on market of 11 days, followed by Albany (16 days) and Geraldton and Bundaberg (both 18 days).
Conditions were weakest in Regional NSW, where Bowral-Mittagong recorded a median of 86 days, ahead of Batemans Bay (70 days) and St Georges Basin-Sanctuary Point (66 days).
| Highest quarterly growth |
6.4%
Kalgoorlie – Boulder (WA)
|
| Highest annual growth |
32.7%
Kalgoorlie – Boulder (WA)
|
| Shortest days on market |
10 days
Kalgoorlie – Boulder (WA)
|
| Lowest vendor discounts |
1.9%
Albany (WA) and Dubbo (NSW)
|
| Highest change in annual sales vols |
42.4%
Traralgon – Morwell (VIC)
|
| Lowest quarterly growth |
-3.3%
Coffs Harbour (NSW)
|
| Lowest annual growth |
-0.9%
Bowral – Mittagong (NSW)
|
| Longest days on market |
67 days
Batemans Bay (NSW)
|
| Highest vendor discounts |
5.1%
Bowral – Mittagong (NSW)
|
| Lowest change in annual sales vols |
-22.7%
Geraldton (WA)
|
Rents moderate
Regional rental growth eased to 1.1% in the three months to July, down from 1.8% in the prior quarter and marginally below the 1.2% increase recorded across the combined capitals.
Albany (3%), Toowoomba (2.9%), and Kalgoorlie-Boulder (2.8%) posted the strongest rental gains. Seven SUAs recorded rent declines, led by Hervey Bay (-1.1%), Mildura-Buronga (-0.7%), and Maryborough and Mount Gambier (both -0.5%).
| Highest quarterly rental growth |
3.0%
Albany (WA)
|
| Highest yearly rental growth |
13.4%
Albany (WA)
|
| Highest gross rental yield |
7.7%
Kalgoorlie – Boulder (WA)
|
| Lowest vacancy rate |
0.8%
Lismore and Forster – Tuncurry (NSW)
|
| Lowest quarterly rental growth |
-1.1%
Hervey Bay (QLD)
|
| Lowest yearly rental growth |
0.6%
Hervey Bay (QLD)
|
| Lowest gross rental yield |
3.5%
Bowral – Mittagong (NSW), Sunshine Coast (QLD) and Busselton (WA)
|
| Highest vacancy rate |
3.5%
Busselton (WA)
|
"Rental growth has moderated alongside broader housing market conditions, but vacancy rates remain relatively tight across many regional centres," Burg said. "Limited rental supply continues to support rents in many markets, even as demand has become more balanced."
Regional vacancy rates stood at 1.9% in July, compared with 1.7% across the combined capitals. Lismore and Forster-Tuncurry recorded the tightest regional rental markets, both at 0.8%, followed by Warrnambool in Victoria at 0.9%.
Gross rental yields held at 4.2%, above the 3.6% recorded across the combined capitals, with Kalgoorlie-Boulder posting the highest yield among major regional markets at 7.7%.
Want to be regularly updated with mortgage news and features? Get exclusive interviews, breaking news, and industry events in your inbox – subscribe to our FREE daily newsletter. You can also follow us on Facebook, X (formerly Twitter), and LinkedIn.