Mortgage applications using open banking data see over threefold increase on NextGen

Open banking has quietly become a standard part of how Australian mortgage brokers work, with new data confirming the shift is accelerating faster than most of the industry anticipated.
Frollo’s State of Open Banking 2026 report, released this week, shows that lending applications using open banking data grew 234% through NextGen’s ApplyOnline platform in the 2025-26 financial year. One in ten home loans processed through the platform now uses open banking data.
Active Consumer Data Right (CDR) authorisations reached over 1.3 million in June 2026 – nearly five times the volume recorded two years prior, with consent volumes growing 4.83 times in the same period and no sign of a plateau.
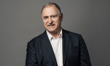
Frollo, an Australian Government Accredited Data Recipient (ADR) under the CDR, described the moment as a turning point. Tony Thrassis (pictured), head of open banking markets and compliance, said: “The foundations are in place, and the momentum is real. The question is no longer whether Open Banking works. It’s how quickly we can make it work for everyone.”
What ignited the surge
The growth did not arrive by accident. It was driven by a convergence of broker adoption, aggregator integration, and a value proposition that became impossible to ignore once brokers experienced it firsthand.
At its core, open banking removes the most time-consuming part of a loan application – the collection and verification of a client’s financial data. Where income and expense verification once required days of statement chasing, lender portals and manual data entry, the same information now arrives verified and formatted within minutes of a client granting consent.
Lenders working with NextGen have found that open banking reduces processing time from an average of six days to a matter of minutes, while improving compliance and eliminating the risk of manipulated bank statements by sourcing data directly from financial institutions.
For a broker writing ten loans a month, that recovered time amounts to roughly seven hours of administration. For one writing twenty, it is closer to a fortnight’s worth of hours annually – capacity redirected to more clients, more complex cases, or simply a better quality of conversation with the ones already in the pipeline. As artificial intelligence (AI) makes document fraud progressively easier, the security benefit compound further. Verified data from the source cannot be faked.
Lending the clearest success story
Usage has more than doubled in a year, and lending is where the proof is most visible. Beyond Bank Australia, the first branch-based lender to bring open banking into its branches, is processing applications 50% faster than under its previous process.
Wendy den Hartog, chief operating officer at Beyond Bank Australia, described the shift plainly: “It’s no longer whether it’s something that you want to adopt. It’s about how quickly organisations can take the services and embed them into core lending processes.”
That shift is already reshaping what brokers can expect from lenders who have committed to the technology – and raising the bar for those who have not.
All of this growth happened voluntarily, one client consent at a time. Australians are choosing open banking in growing numbers because the experience and the outcome are good enough to earn that agreement.
But the consent journey still has friction, and simpler first steps at the bank will help more people see consent through. Across three of the largest banks examined in the Frollo 2026 report, around two in three abandoned consents happen in the first two steps of the authentication process – when consumers identify themselves and complete authentication.
Brokers who explain clearly what is being shared, why, and that access can be revoked at any time are seeing measurably better completion rates. The difference is not technology – it is guidance. That is something every broker can act on today, without waiting for a regulatory fix.
Looking forward
The lending opportunity open banking has already created is only the beginning. The system is expanding – and for brokers, that expansion translates directly into a richer, faster, and more complete picture of every client they sit across from.
The most immediate change is the range of lenders now inside the CDR. As non-bank lenders entered the system in mid-2026, brokers who write loans for clients who sit outside mainstream lending criteria now have access to standardised product data from those lenders in the same way they access major bank data. Comparing options across a broader market, with consistent and verified information, becomes significantly more straightforward.
Looking further ahead, there is a strong case being made to include Australian Taxation Office (ATO) data within the CDR. If that proceeds, a broker will be able to access a client’s verified income directly from the ATO – within the same consent-driven process already used for bank data. That removes one of the most time-consuming steps in a loan application without adding any complexity to the client.