Mortgage rates above 7% and tight affordability sidelined California buyers

California homebuyers stepped back in October, and the state’s housing market felt it. Elevated mortgage rates and stretched affordability slowed California home sales to their weakest pace in nearly three years, the California Association of Realtors (CAR) reported.
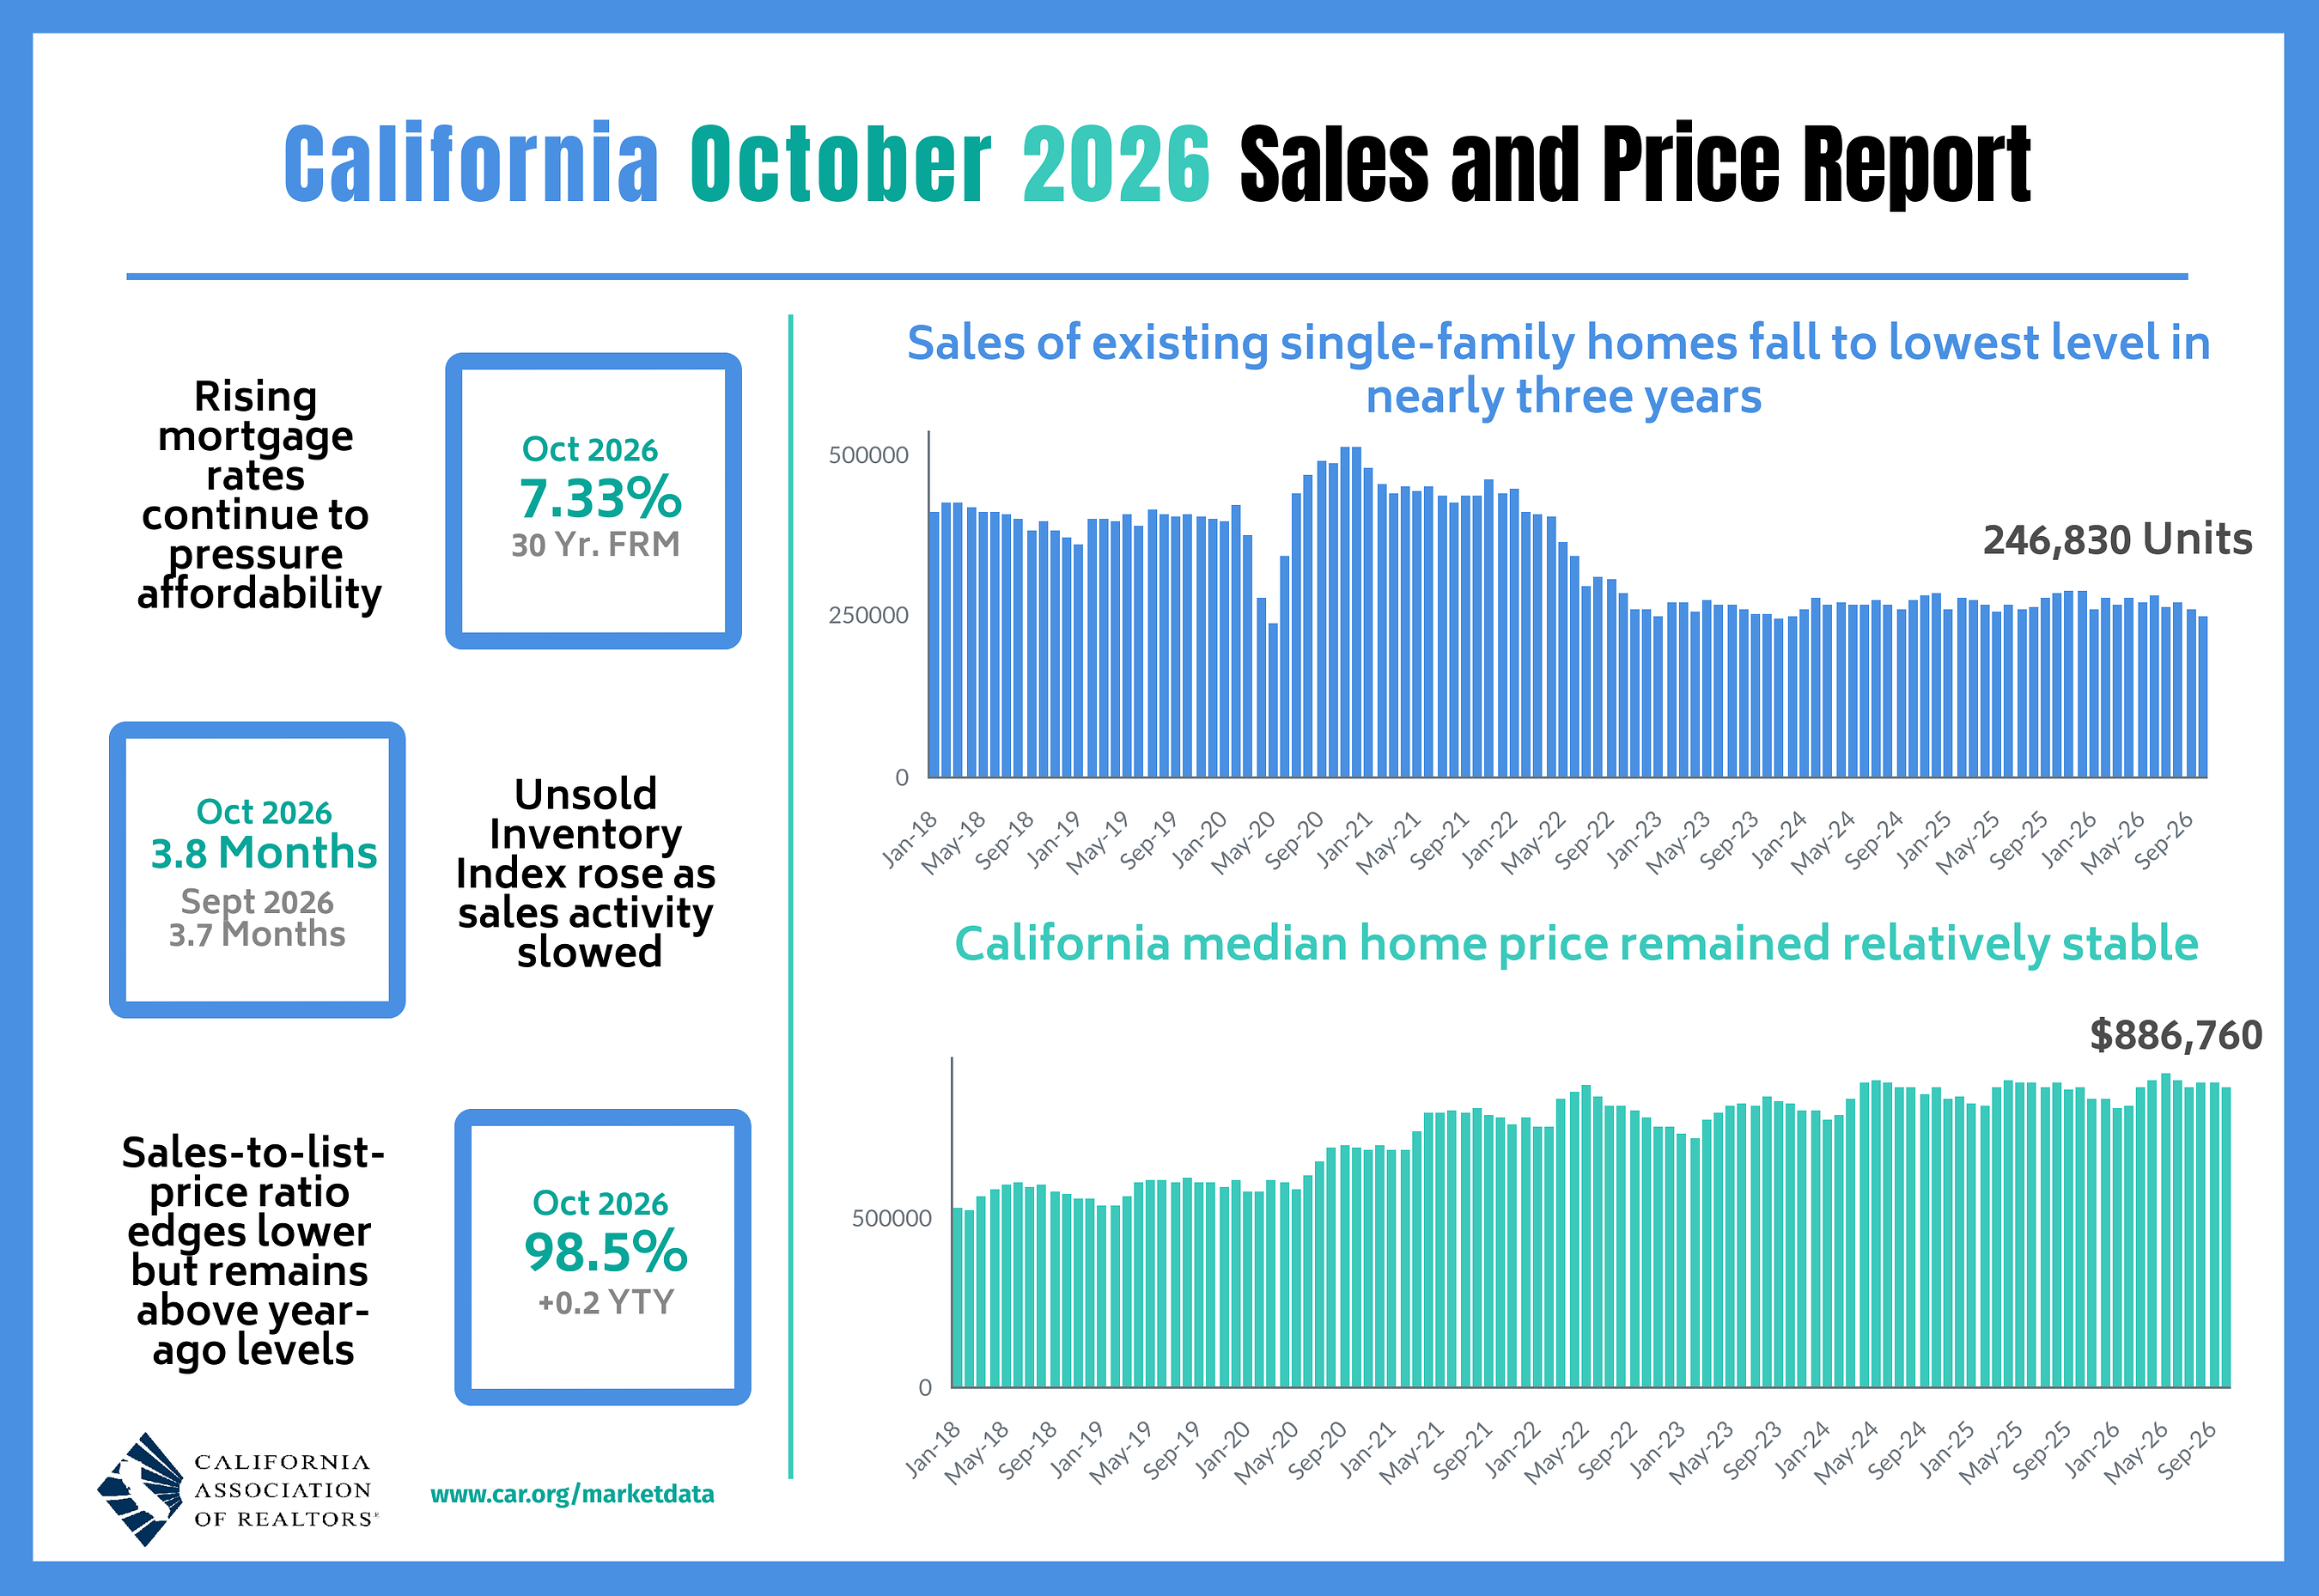
Closed sales of existing single-family homes ran at a seasonally adjusted annual rate of 246,830, down 5.2% from September and 12.7% from October 2025.
Sales have stayed below 300,000 for 49 straight months.
The 30-year fixed-rate mortgage averaged 7.33% in October, up from 6.86% in September and 6.25% a year earlier, according to C.A.R.’s calculations based on Freddie Mac data.
Mortgage applications fell 2.3% for the week ended Nov. 13, as the average 30-year fixed rate climbed to its highest level in three weeks, the Mortgage Bankers Association (MBA) said https://t.co/iirUs1skSF
— Mortgage Professional America Magazine (@MPAMagazineUS) November 18, 2026
Why are California home sales falling?
The slowdown was broad, CAR data showed. Sales fell by double digits year over year in six of seven price segments, led by homes priced between $750,000 and $999,999, which dropped 20.7%.
The $1 million to $1.99 million tier fell 19.7%. Only homes at $2 million and above gained, edging up 0.7%.
Regionally, Southern California sales declined 18.9% and the San Francisco Bay Area 12.1%.
Prices held firm. The statewide median was $886,760, down 1.4% from September and essentially flat from $887,330 a year earlier.
CAR President Mark Peterson, a Southern California broker, said buyers reassessed what they could afford after rates jumped in late September, while steady prices suggest sellers remain confident.
What does rising inventory mean for brokers?
Supply is building. CAR’s Unsold Inventory Index, which measures how many months it would take to sell current listings at the prevailing pace, rose to 3.8 months from 3.2 months a year ago.
Active listings were 6.6% higher than in October 2025. Homes sold in a median of 29 days, down from 32 days, and the statewide sales-price-to-list-price ratio was 98.5%.
Nationally, the National Association of Realtors (NAR) reported existing-home sales falling to their lowest level since 2010, at a 3.75 million annual rate.
Yury Shraybman, an originator at Innovative Mortgage Brokers in Pennsylvania, told Mortgage Professional America that “getting consistently below 7% would probably get people’s attention.”
Relief may come slowly. Persistent inflation, Mortgage Bankers Association (MBA) chief economist Mike Fratantoni in Washington, DC, said, is likely to keep the Federal Reserve “on track to hike rates at future meetings.”
The MBA expects two more increases over the next six months, he said, after the US economy’s 3.4% third-quarter growth beat forecasts.
Jordan Levine, CAR senior vice president and chief economist, said “pent-up demand continues to build as many prospective buyers stay on the sidelines.”
Levine expects buyers to return gradually as geopolitical tensions subside and economic uncertainty eases.
Stay updated with the freshest mortgage news. Get exclusive interviews, breaking news, and industry events in your inbox, and always be the first to know by subscribing to our FREE daily newsletter.