One broker says borrowers who could go conventional are choosing non-QM
Mortgage rates are the most talked-about topic in the mortgage industry that nobody wants to be talking about, especially when they’re higher than economists forecast coming into the year.
The latest numbers from Freddie Mac showed a 30-year rate at nearly a three-year high of 7.28%. As bond yields climbed again Monday, there will need to be a reversal to avoid another increase when the new rates are released this Thursday.
With conventional mortgage rates increasing, rates on some non-qualified mortgages (non-QM) have increased more slowly. This is causing a market shift, with some non-QM and non-agency products competing with, and in some cases beating, agency loan rates.
One broker said originators who lean on conventional financing may want to compare non-QM pricing.
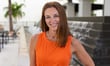
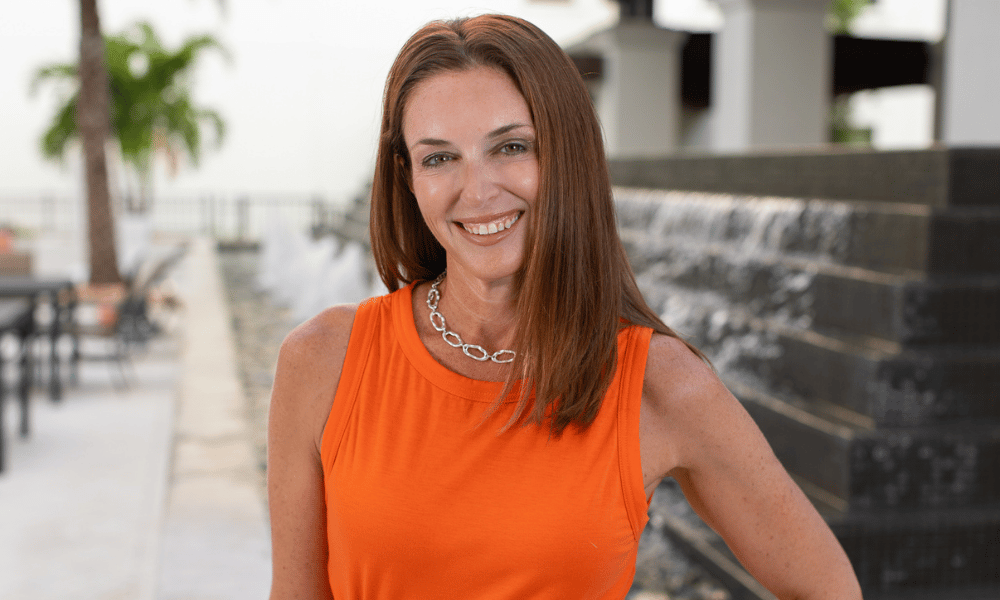
Jacy Bloom (pictured top), owner and mortgage broker at Bloom Mortgage Solutions, said she has been running that comparison on her own files in recent weeks.
"I had somebody a couple of weeks ago that I put into a non-QM loan because it strictly was a better rate," Bloom told Mortgage Professional America. "And a better deal for him versus going conventional. That's a primary residence."
The gap keeps widening
Bloom described a recent investment property deal for a W-2 borrower who could document income in full. She started with conventional financing a few weeks before the borrower went under contract, then suggested a full-doc non-QM option.
"At that point in time, the rates were about an eighth of a point difference between conventional and non-QM financing, with non-QM financing being the better of the two," she said. "Fast forward to when they went under contract, I ran the numbers, and it was three-quarters of a point different. So huge difference. Rates in both aspects obviously went up, but the conventional was literally three-quarters of a point higher than going non-QM."
She priced the loan with a couple of non-QM lenders, and every one of them came in below conventional, Bloom said.
One of the biggest differences Bloom cites is the volatility of pricing for agency loans compared to the non-QM market.
"With conventional financing, the rates can change five times a day, especially when you have market conditions as they have been over the last few weeks," she said. "But the non-QM market, they just don't change as quickly. Have they gone up? Absolutely. But they don't react as quickly to go up. It's a little bit of a slower process."
Why some brokers hesitate
Bloom said the pricing shift has not changed how every broker feels about non-QM. She heard that in person at a dinner during the Association of Independent Mortgage Experts (AIME) Fuse event in Austin.
"I know a lot of other mortgage brokers are scared of non-QM," she said. "I was sitting across the table from these great brokers who specialize in VA. One of the guys said, 'I'm terrified to do non-QM. I'm stressed out. I don't like it. I'm worried for my client. I try to stay away from that as much as I possibly can.' And I'm like, why? I think some of it's because he doesn't know the programs as well."
She expects more brokers to take on non-QM lending, especially if they see potential deals fall through in a rising rate environment.
"I tell them all the time, they're losing so much business by not embracing it," she said. "You're either going to learn it, or you're going to lose deals. It's pretty simple."
Clients also have to be educated on the potential benefits of looking at non-QM financing.
"I don't think the majority of clients, like this client that I locked in, they never would have thought, 'Oh, if I went into non-conventional financing, I'd be saving three-quarters of a point on my rate,'" she said. "It's not necessarily knowledge that people who are not in the industry have. I try to put that information out there, but I'm only one person."
Non-QM already makes up most of Bloom's own business, with only two conventional loans in her pipeline as of early October. How long the current pricing advantage will last is a different matter.
"It has been interesting seeing that people who could go conventional find it makes more sense to go non-QM right now," she said. "That could just be a pattern for the next 30 days, and then it could change. If rates get more favorable, that will probably change, and it'll go back to how it normally is."
Stay updated with the freshest mortgage news. Get exclusive interviews, breaking news, and industry events in your inbox, and always be the first to know by subscribing to our FREE daily newsletter.