Apex's Kathy Dey says the savings can run into six figures and fund better pricing

The latest data showing money lost on originated mortgage loans, combined with an increase in production expenses, has the industry looking for solutions.
Independent mortgage banks and mortgage subsidiaries of chartered banks lost an average of $30 on each loan they originated in the third quarter, the Mortgage Bankers Association (MBA) reported Tuesday, a swing from a $973 profit in the second quarter. The MBA warned that staff reductions and other cost-cutting measures may accelerate through the rest of the year and into early 2027.
Lenders’ production expenses averaged $11,615 per loan, up $679 from the second quarter, while the number of production employees per firm stayed relatively flat despite lower volume.
One area where brokers could focus on savings is processing costs. A salaried processor is part of a broker’s operating expenses, while contract processing replaces that salary with a per-file fee charged to the borrower as part of the closing costs.
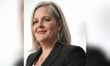
Kathy Dey (pictured top), director of operations at Apex Processors and a 32-year industry veteran, said converting a team to contract processing saves brokers $200,000 to $300,000 a year. She shared her thoughts in a breakout session at AIME Fuse.
"All of these speakers are telling you how to generate more revenue, right?" Dey told Mortgage Professional America. "I'm here to show you how to save."
Cutting overhead per file
Many brokers do not realize they can convert an in-house processor to contract, Dey said. The broker stops paying the salary, and the processing fee is charged to the borrower as part of the closing costs.
"On average, you think $700 to $1,500 per file is what it costs for a processor," Dey said.
At five closings a month and the high end of that range, the savings come to $7,500 a month, or $90,000 a year. Loan officers who are paid on commission rarely see the cost, since it comes out of their commission.
"You don't see it, so you don't miss it, kind of like 401(k), right?" Dey said. "But when you see it back in there, that's when it makes the impact."
Brokers often worry that a visible processing fee will scare off a borrower. Dey said her own broker-owner felt that way when she first learned about contract processing.
"The reality is borrowers do not pay attention that much to closing costs unless they're like an investor and they've done this 10, 15 times over," Dey said. "It's the cost of doing a loan. Borrowers are more rate-conscious or cash-to-close. That's what they're fixated on, right? Not the itemized fees."
As a branch originator, Dey discovered contract processing after the pandemic-era refinance boom ended, when her branch could no longer afford its processors.
"I'm 32 years in this industry," Dey said. "It's volatile. It is a roller coaster. Feast or famine, right? So prime example right now, when you can cut cost on overhead, seize the moment."
Better pricing, better files
The money does not have to end up in a broker's pocket, Dey said. It can go toward more competitive pricing in a market where deals are hard to come by.
"Instead of allotting $1,000 go towards your operational expenses, you can buy the rate down, then they're a little bit more competitive," Dey said. "You can issue a lender credit to help FHA, DPA, help them with the closing costs. So you can actually leverage it to then do a better deal and a better program for the borrower."
Apex now has almost 170 processors, up from 13 a year ago. Many of them are also loan officers who originate a few deals a month and process more.
"I only bring on processors who have self-sourced business," Dey said. "I don't staff processors and fill their pipelines. They come over, I'll blend in and help fill it too, but I want processors that already have established relationships."
When a processor's main brokerage is slow, Dey said, Apex can add files to cover the gap.
"She may be getting 7 to 12 from her main brokerage, and I sprinkle in 5 additional loans a month," Dey said. "She's now hitting her financial needs. She doesn't need to look for a job somewhere else."
Dey, a former underwriter and compliance officer, said processors now learn what underwriters need and collect letters of explanation (LOXs) before a file is submitted.
"I have processors now, they'll tell you all day, I don't submit a file without LOXs," Dey said. "I already know I need address, credit inquiries, large deposits. I know I'm going to need these. Let me get them ahead of time."
Bridging the gap between operations and origination is Dey's stated goal. Loan officers get the credit as the moneymakers and the face of a brokerage, she said.
"You can take as many apps and get as many deals as you want, but if you can't close them, it doesn't make a bit of difference, right?" Dey said. "You're just spinning your wheels in park."
Stay updated with the freshest mortgage news. Get exclusive interviews, breaking news, and industry events in your inbox, and always be the first to know by subscribing to our FREE daily newsletter.