Mortgage professionals brace for a Bank of England base rate increase and urge clients not to panic

The Bank of England's Monetary Policy Committee (MPC) meets on Thursday for what could be the most consequential base rate decision in over a year.
The base rate has been held at 3.75% since December 2025, when it was cut from 4%, and has remained at that level through six consecutive meetings. At September's meeting, the MPC voted 6-3 to hold, with three members – Catherine Mann, Megan Greene, and Huw Pill – voting for a rise to 4%.
That split vote looks more significant now that UK Consumer Price Index (CPI) inflation climbed to 3.5% in September, up from 3.1% in August and higher than forecast, driven largely by a surge in motor fuel prices.
With financial markets pricing in a series of increases that could take the base rate to 4.75% by mid-2027, many in the mortgage industry are bracing for a first upward move on Thursday.
Stay ahead of the UK mortgage market. Subscribe to the Mortgage Introducer daily newsletter for broker news, rate updates, and the industry latest delivered to your inbox every morning.
Market already positioned for a rise
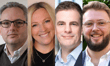
Those working in the UK mortgage market will not be surprised if the MPC shifts direction this week. Robert Gardner (pictured top left), chief economist at Nationwide, said much of the anticipated move is already reflected in swap rates – the interest rates at which banks lend to each other, which are the key driver of fixed-rate mortgage pricing – and that the direct impact on fixed-rate lending should therefore be modest. "That change by itself shouldn't have much of an impact on fixed-rate mortgage lending," he told Mortgage Introducer. "It may have implications for variable-rate offerings, but the quarter-point is fairly modest."
Gardner acknowledged that financial markets are now pricing in bank rate getting towards 5% over the next year or so, but cautioned that this may not tell the full picture. The Bank of England's own monetary policy report has suggested that much of the movement in futures markets reflects risk premia rather than a straight expectation that bank rate will follow that trajectory.
If energy prices begin to ease, as many hope, those expectations could moderate – bringing swap rates down with them and offering some relief to fixed-rate mortgage pricing further down the line. "I am not sure there will be the need for bank rate to rise as much as financial markets are currently projecting," Gardner said. "Wage growth has been well behaved. There is not really much evidence of second-round effects from these higher energy prices."
Joe Stallard (pictured top right), managing director at House and Holiday Home Mortgages, echoed that view, saying the market's reaction to any increase tends to be overstated. "A lot of it is based on swap rates, and a lot of it is already baked into product pricing," he told Mortgage Introducer. "It's rare that we see knee-jerk reactions off the back of an announcement to pricing."
Stallard added that a short-term rise, if it brought greater stability and set the conditions for reductions next year, was something most in the market would ultimately accept. "If it's a short-term measure to get a bit of stability, to allow for a stronger market with hopefully some rate reductions next year, I think happening at this time of year, that's something that most people would take."
What does a rate rise mean for tracker and fixed-rate borrowers?
Katherine Stagg (pictured top middle left), founder and managing director at Stagg Mortgage Services, said her priority ahead of Thursday is keeping clients calm. With 25 years in the industry, she said media coverage can compound anxiety more than the change itself. "I have just told my clients personally not to panic but not to ignore it," she told Mortgage Introducer. "A change of the Bank of England base rate doesn't necessarily affect fixed mortgage rates. The fixed rates are a per cent higher, so you are still better off with your trackers."
A tracker mortgage rate moves directly in line with the Bank of England base rate and is typically set at a fixed percentage above it. Stagg said her firm has written more tracker business in recent months than at any point in the last decade – a trend reflected across the wider market, where tracker mortgages have surged as the base rate outlook shifts.
The calculus, Stagg said, remains favourable for clients who can tolerate some degree of uncertainty. She draws a clear line at first-time buyers, however, as they should always be steered towards the security of a fixed rate regardless of current market conditions. "I would definitely 100% make sure they were on a fixed. They are starting out on their own and they have got a lot of bills going out. The stability of having a fixed, even if it is higher for a couple of years, would be better."
Her wider message is one of perspective. Stagg has worked through previous rate cycles and said the current environment, while challenging, is not without precedent. "It’s just about reassuring people that there are better things to come.”
What brokers should be doing now
David Hollingworth (pictured top middle right), associate director at L&C Mortgages, said that for many existing homeowners Thursday's decision will be the defining piece of news of the week, and that brokers have already been playing a central role in helping borrowers make sense of a difficult environment. Clients who locked in low fixed rates during the historic lows of 2020 and 2021 are now coming to the end of those deals and facing a very different market. "There are people coming off sub-2% rates whose focus will be on what can I do, how much is it going to cost, and is there anything I can do to mitigate that," he told Mortgage Introducer.
Hollingworth believes that while rates have been more stable in recent months, the direction of travel remains a concern for many borrowers. Brokers, he said, have been instrumental in helping clients secure the best available deal before any further repricing. "Brokers will have been instrumental in helping them get the best that they possibly can," he said. "It is a little bit more stable at the moment, and long may that continue."
The bigger picture: stability, not panic
The message from the frontline is consistent. Clients should not make decisions based on the announcement alone. With mortgage rates expected to remain elevated through late 2026, and lenders already accounting for the likely move in their pricing, the immediate pressure facing brokers is more about communication and reassurance than product strategy.
The rate environment will shift again, and the question is when, not if. As Stagg put it: "There is still a mortgage market there. It is just a case of getting the right advice and planning."
Want to be regularly updated with mortgage news and features? Get exclusive interviews, breaking news, and industry events in your inbox – subscribe to our FREE daily newsletter. You can also follow us on Facebook, X (formerly Twitter), and LinkedIn.